

What Does It Mean to Be Wealthy in Japan vs. the U.S.?
Original post: May 6, 2025
Updated post; Oct, 12, 2026
I’m not here to say one country is better than the other—I love both the U.S. and Japan. But having lived in both, I’ve come to see that “being wealthy” is about more than just how many dollars or yen you have in the bank. It’s about how that money translates into daily life—shaped by cost of living, social systems, cultural values, and most importantly, your own sense of what matters.
You don’t need to be ultra-rich to live a rich life in Japan. Compared to the U.S., wealth here often feels more attainable, more grounded. In the U.S., “wealth” can feel elusive, tied to constant striving. But in Japan, it may be easier to find your own version of wealth.
Let’s explore these differences through data, personal experiences, and a broader cultural lens.
Update Note (2026 Context): Why Wealth Shifted in Japan
| Key Metric | Past Baseline | 2026 Context |
|---|---|---|
| Affluent Households |
Approximately 1.39 million households
(2021)
|
Approximately 1.65 million households
(Latest cited NRI estimate; verify report year)
|
| USD/JPY Exchange Rate |
USD 1 = JPY 100
USD 1 million = JPY 100 million
|
USD 1 = JPY 150
USD 1 million = JPY 150 million
Illustrative comparison, not a live exchange rate.
|
| Wealth Classification | Assets valued in JPY may fall within different wealth bands as their value changes. | A weaker yen can increase the JPY value of USD assets, potentially moving a household into a higher wealth band even if its USD balance remains unchanged. |
Takeaway for Retired Cross-Border Couples
A weaker yen can increase the JPY value of USD savings and investments, potentially providing more yen for living expenses in Japan. However, exchange rates can reverse, investments can lose value, and a higher JPY balance does not guarantee greater purchasing power or protect principal.
Source note: Verify the NRI household estimates, report year, and wealth-band definitions before publication. Exchange rates are illustrative.
This blog covers:
Defining Wealth: A Numbers Game with Context
Daily Life: Where Your Money Takes You
Social Systems: The Safety Net Factor
Wrap up
1. Defining Wealth: A Numbers Game with Context
Let’s start with how wealth is measured in each country.
🇯🇵 In Japan, the Nomura Research Institute (NRI) defines wealth tiers based on net financial assets (total financial assets minus liabilities, excluding homes and pensions). According to their 2023 data:
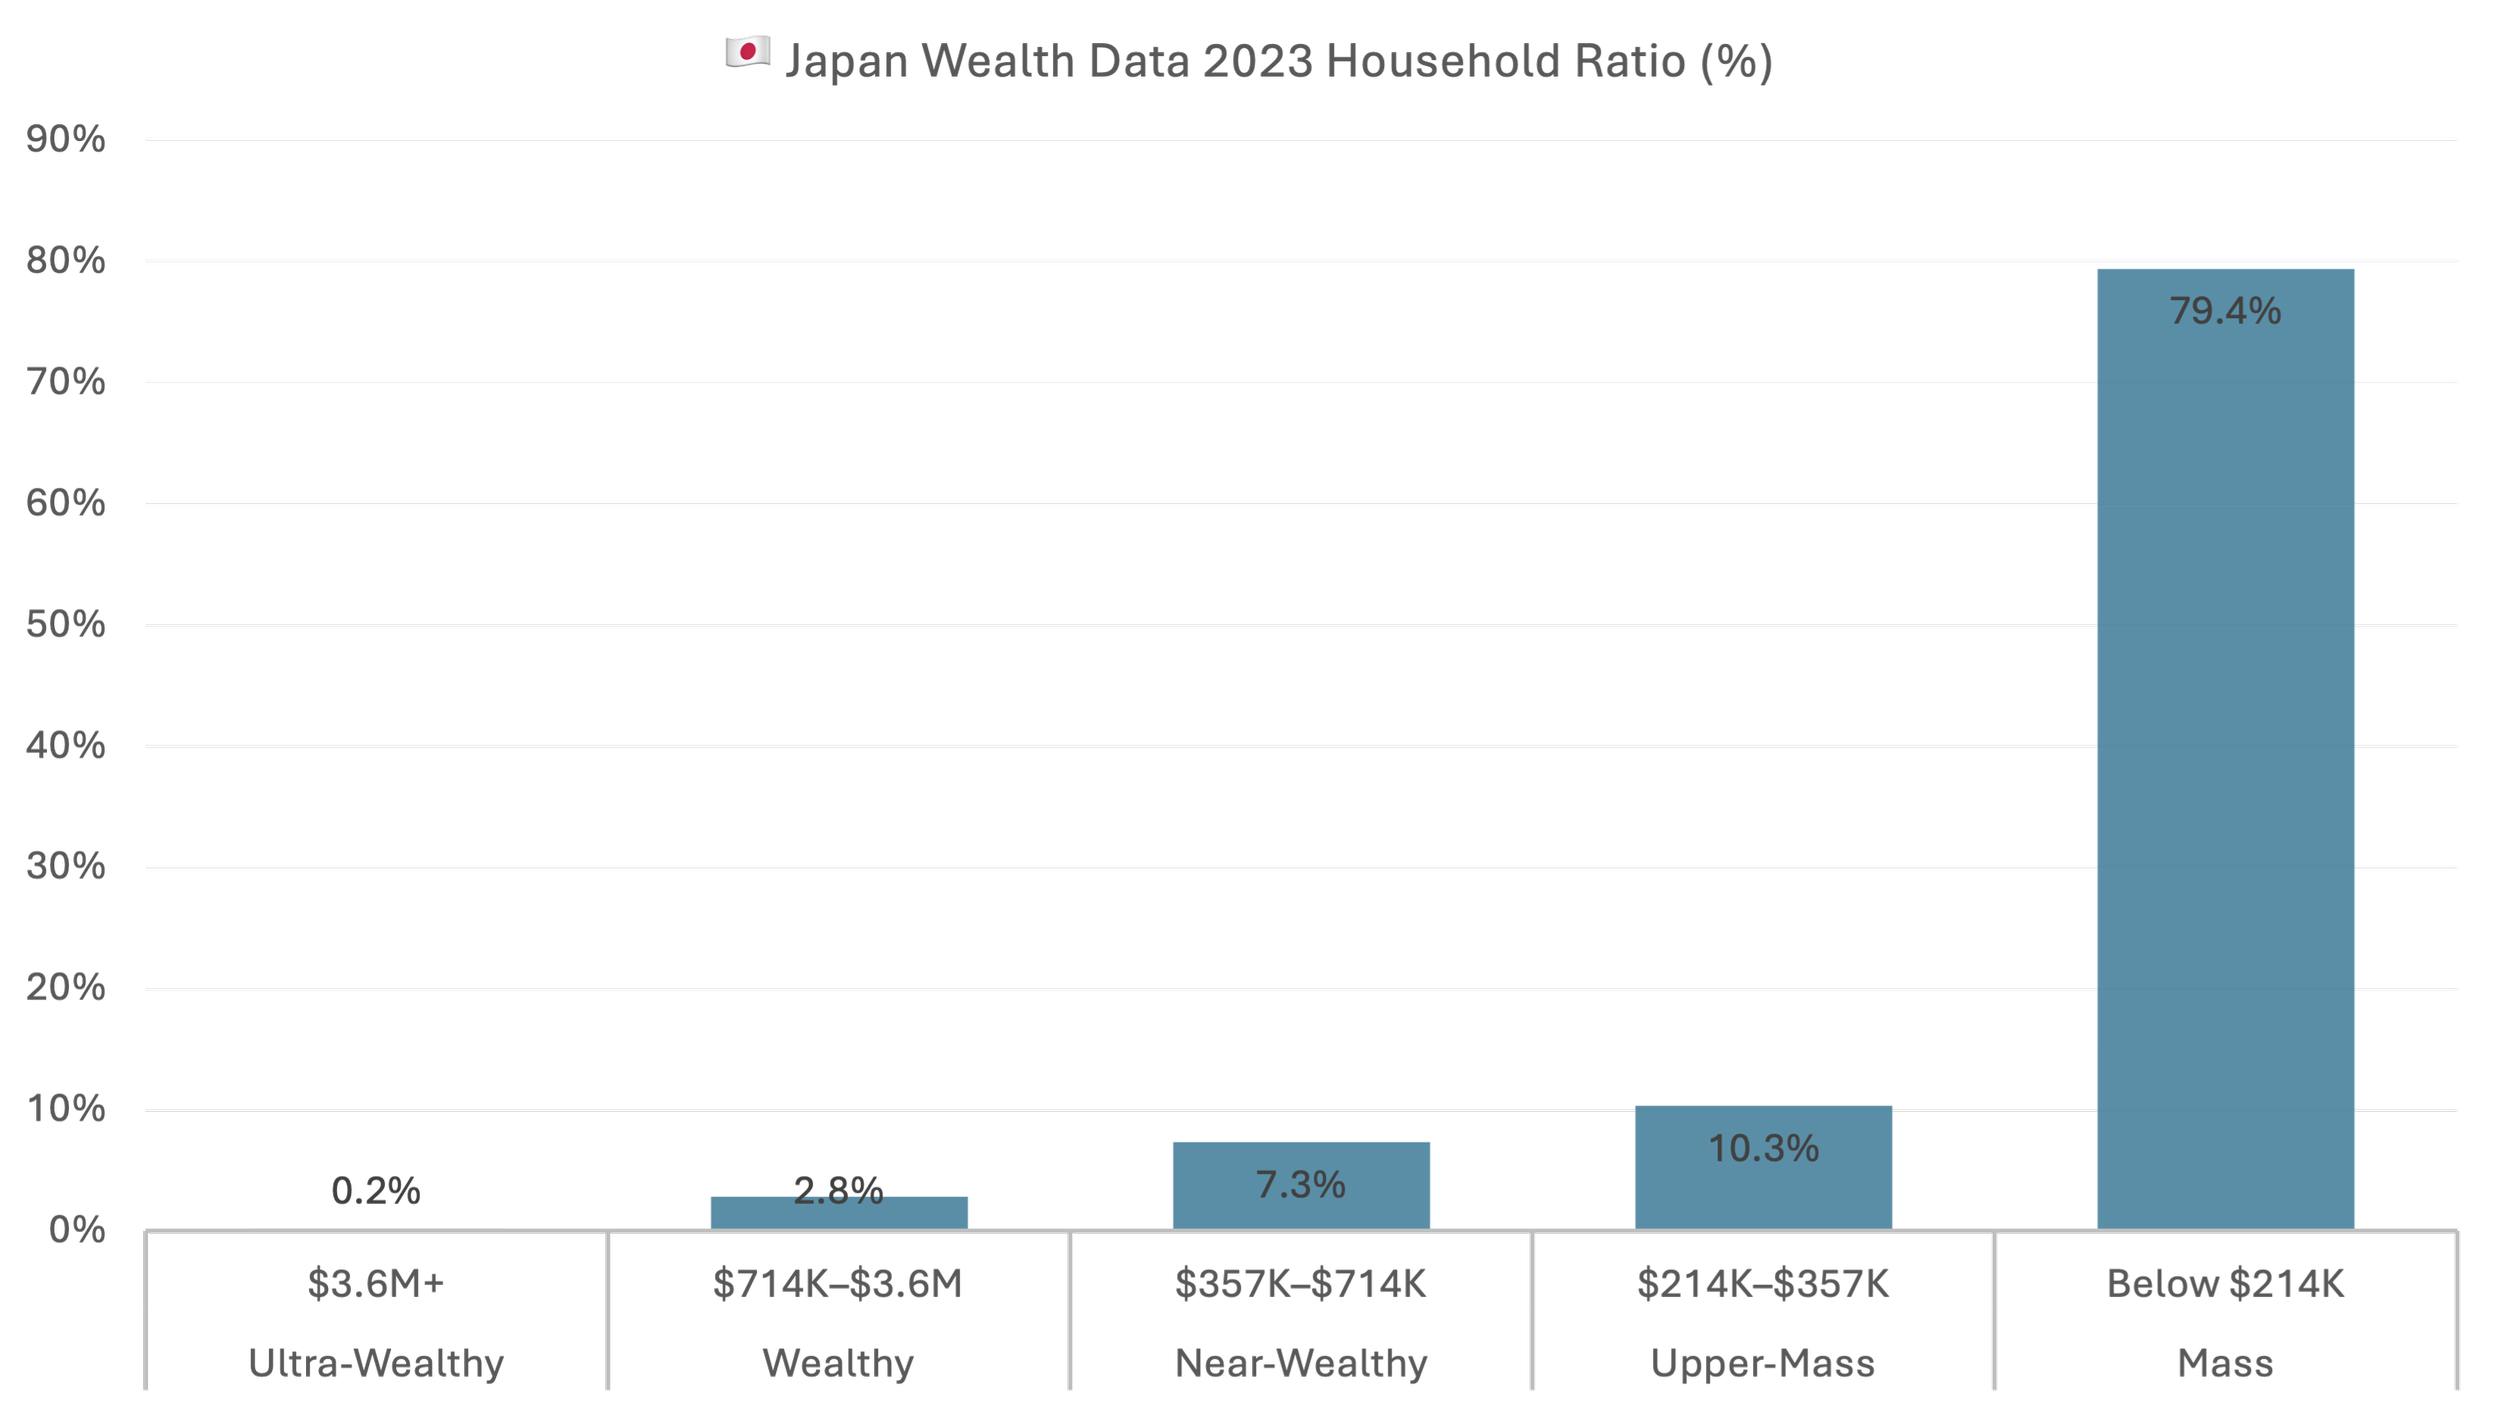
NRI’s exclusion of homes might underestimate wealth for middle-class households with significant real estate—a common asset in Japan.
🇺🇸 In the U.S., wealth is typically measured by total net worth asset (including homes and investments).
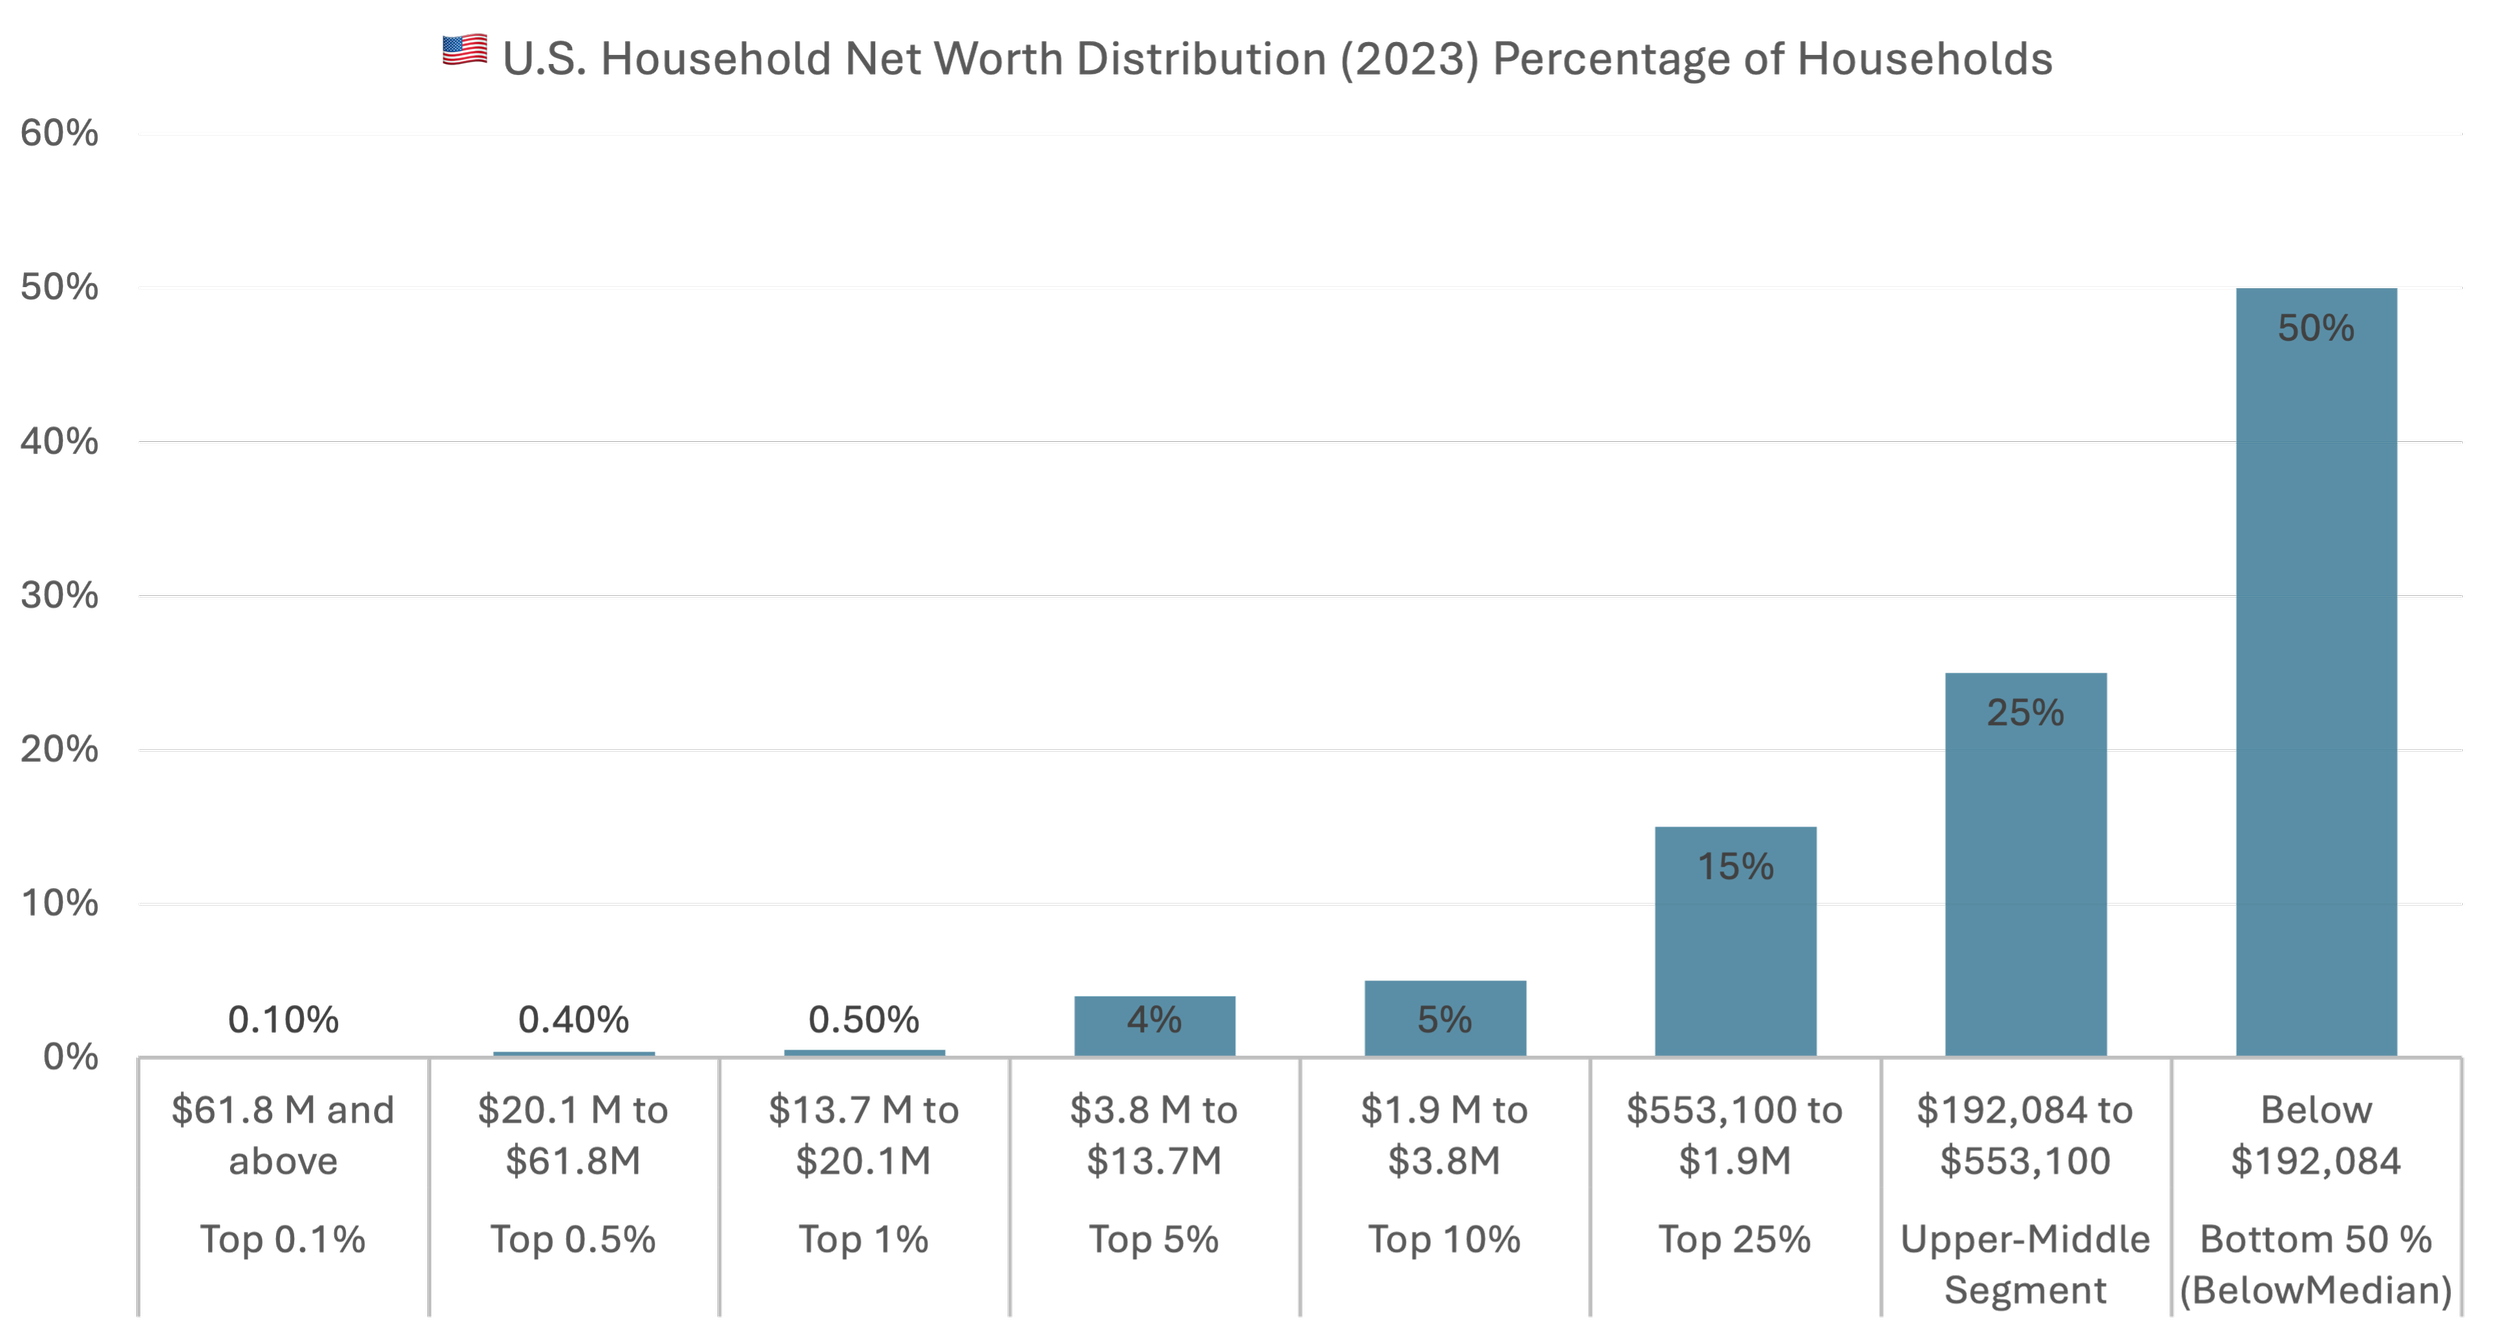
Source: Federal Reserve's Survey of Consumer Finances and compiled by DQYDJ.
Note: The percentages of “Top” Bracket are cumulative; for example, the Top 5% includes the Top 1%.
Bottom line: In Japan, 89.7% of households fall into the "mass" category (net worth under USD333K), compared to 75% in the U.S. This means Japan has a broader financial middle.
In the U.S., roughly 23,684,985 households – about 18.0% of American households – was a millionaire household. Median household net worth in the United States was $192,084.
2. Daily Life: Where Your Money Takes You
Wealth isn’t just a number—it’s what it buys you. Let’s compare how income translates into lifestyle in Japan and the U.S., focusing on practical realities.
🇯🇵 In Japan/Snapshot: an annual income of ¥20 million places you in the top income bracket, often associated with upper management roles like a Director (部長) at a large firm. For context, Japan’s national average income in 2025 is ¥4.78million.
Related article
Japan Cost of Living Blueprint 2026
How Much to Retire in Japan as an Expat: 2026 Costs, Visas, and Realistic Budgets
3. Social Systems: The Safety Net Factor
Social systems play a huge role in how wealth feels, especially for medical, long-erm care and retirement. Let’s compare Japan and the U.S. in this critical area.
Health Insurance and long-Term Care Insurance
🇯🇵 In Japan/Snapshot: If you are employed, the premium is split equally between you and your employer, with each paying 50%. This covers medical, dental, and vision care, with a 30% co-payment for most services. If you’re not employed, you can enroll in Japan’s National Health Insurance (NHI).
Then, Japan’s High-Cost Medical Expense Benefit is a government program that limits how much individuals have to pay out of pocket for medical care each month. If your monthly medical expenses exceed a certain threshold, the excess amount is reimbursed.
In addition, Japan’s universal long-term care insurance (Kaigo Hoken), mandatory from age 40 for all residents (including foreigners registered over 3 months), covers in-home nursing, senior daycare, wheelchair rentals, and group homes. Even foreigners who join late—say, at 65 after staying in Japan for over three months—can access long-term care benefits as long as they pay premiums, significantly reducing the financial strain of aging.
Want to know more? Check out my blog below:
The Cost of a Cross-Border Life: Managing Complexity and Spending Wisely in Japan
Retirement Savings
🇯🇵 In Japan: In 2019, Japan’s Ministry of Health, Labour and Welfare recommended that retired couples have JPY 20 million in savings. The amount needed varies depending on life expectancy and lifestyle. However, among two-person households in their 60s, the average financial assets held were JPY 20.33 million, while the median was only JPY 6.5 million.
Source: Financial Services Agency of Japan’s J-FLEC (Japan Financial Literacy and Education Corporation), Public Opinion Survey on Household Financial Behavior (2024) — Financial Asset Holdings (Including Households Without Financial Assets), by Age of Household Head: Households with Two or More Persons, Age 60–69.
Pension
🇯🇵 In Japan: At age 65, the average monthly benefit is approximately JPY 61,000 for the National Pension and JPY 150,000 for Employees’ Pension Insurance. These benefits can be modest relative to living expenses, particularly in high-cost areas such as Tokyo.
This limited pension income highlights the importance of personal savings. As mentioned earlier, many older adults in Japan continue working well past retirement age to maintain financial stability.
4.Wrap up
Wealth Is Not Just What You Accumulate. It Is What Your Wealth Allows You to Do.
According to Nomura Research Institute’s 2023 estimates, Japanese households with net financial assets of JPY 100 million to less than JPY 500 million are classified as “affluent.”
However, when it comes to retirement, the amount you have saved is only part of the equation.
Paying off your mortgage before you stop working can reduce the pressure on your monthly budget. If your regular income covers your living expenses, you may not need to draw heavily on your financial assets.
But there is another question worth asking: What is the purpose of accumulating wealth if you never feel able to use it?
Saving provides security. My father, for example, still saves.
Yet learning how to spend money thoughtfully is also a skill. As your financial position changes, it is worth asking whether your money is supporting the life you want to live.
Aki | Japanese | Former Head of HR in Global Finance
I believe building a long-term life in Japan requires seeing the bigger picture.
By understanding how visa, healthcare, taxes, retirement, senior care, inheritance, and family decisions fit together, you can make informed decisions and take calculated risks.
